Helping you better understand securitized credit
We expect the currently addressable US$1.3 trillion securitized credit market available to European investors to continue to grow.
Below we explore why you should invest, the structural protections, ways to access and risks to consider.
Download the full primer which also explains what securitized credit is, how it works, the main categories and the credit opportunity set for European investors.
Click here to discover more insights on our securitized credit landing page.
Why invest in securitized credit?
Securitized credit can offer a number of key benefits for investors:
- Attractive income generation: Securitized credit typically offers a higher yield relative to other comparably rated traditional fixed income investments.
- Structural protection: these features create multiple sequential layers of loss absorption, protecting senior bondholders even in a scenario in which a meaningful proportion of the underlying collateral defaults.
- Diversification benefits: securitized credit offers greater diversification across borrowers, sectors and geographies in the underlying asset pool, reducing single-issuer concentration risk relative to traditional credit. More consumer-oriented collateral also introduces risk factors that are structurally distinct from corporate credit risk, broadening overall portfolio diversification.
- Lower duration than traditional credit exposures: the predominantly floating-rate structure of securitized bonds, and often shorter effective maturities, results in a lower sensitivity to interest rate movements compared to traditional fixed income credit exposures.
- An active opportunity: the nuances between the sub-asset classes, together with market inefficiencies can create opportunities for active managers with specialist knowledge and deep resources to add value. This can include investing across sub-asset classes to capture potential opportunities, and adding greater diversification.
The exact risk and return profile will vary depending on the underlying collateral generating the cash flows for the securities.
What are the structural protections in securitized credit, and why do they differ from corporate credit?
The securitized structure embeds multiple, independent layers of credit protection that are fundamentally different from the single-obligor risk profile of corporate debt. These protections are contractually embedded in deal documentation and enforced through legally ring-fenced special purpose vehicles, rather than being contingent on any single issuer's balance-sheet strength. These include the following:
- Subordination is created through the process of tranching, which divides the capital structure into a hierarchy of bonds – equity, mezzanine, and senior – each with a defined position in the loss waterfall. Losses on the underlying collateral are absorbed first by the equity tranche, then by mezzanine tranches, before any impairment can reach the senior notes. Unlike corporate credit, where recovery depends on an issuer's residual enterprise value at the point of distress, securitized investors benefit from a dedicated collateral pool with contractually defined loss-allocation rules.
- Excess spread – the difference between the interest income generated by the collateral pool and the coupons owed to bondholders plus deal expenses – acts as the first line of defence, absorbing collateral losses on a current basis before any subordination is eroded. It functions as a dynamic, self-replenishing credit enhancement that works in tandem with subordination: excess spread handles routine collateral friction, preserving the structural cushion beneath each tranche for more severe stress scenarios. Corporate bonds have no analogous mechanism that automatically diverts issuer cash flows to absorb losses for the bondholder's benefit.
- Collateral characteristics provide further insulation. In many asset classes – residential mortgages being a prominent example – the borrower holds equity in the financed asset (e.g. a homeowner's deposit and any subsequent price appreciation), which must be fully eroded before a loss reaches the deal. Securitized portfolios also typically comprise hundreds or thousands of individual exposures across borrowers, geographies, and industries, materially reducing the single-issuer concentration risk inherent in corporate bond portfolios.
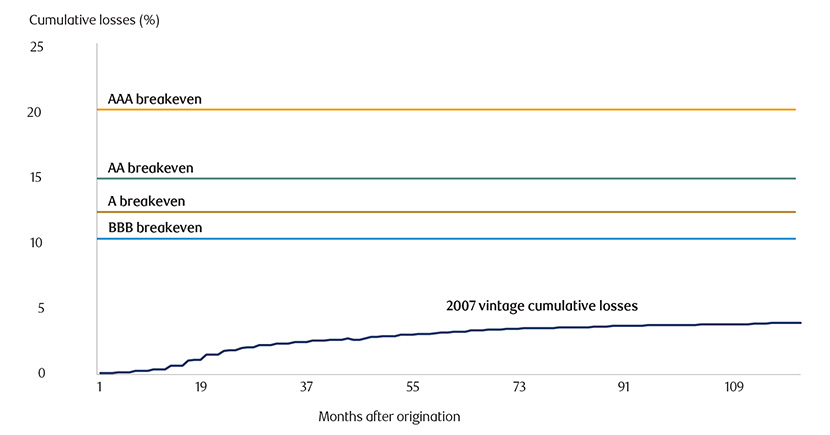
These structures can provide investors with strong protection against losses, even under stressed scenarios. The chart below for UK housing mortgage-backed securities demonstrates the level of cumulative losses required for investors in the different tranches of bonds to experience a loss. Even for mortgages issued in 2007, the most challenging vintage in the last 30 years, did not see more than 5% of cumulative losses, insufficient to impact investment grade tranches, as illustrated in figure 1.
Figure 1: Strong structures protect investors from losses, even under stressed scenarios (UK RMBS example)
Source: RBC BlueBay Asset Management. Illustrative only. This is not a recommendation to buy or sell a particular security.
The broader securitized credit market has evolved since 2007, including greater credit enhancement for example. As a result, for some AAA-rated European RMBS today, up to 80% of the underlying loan pool would need to default before the AAA tranche incurs a loss. This is a scenario that has never occurred in European securitized credit. For certain BBB-rated CLO debt, the loss threshold equates to roughly twice the worst default rates observed during the global financial crisis (GFC).
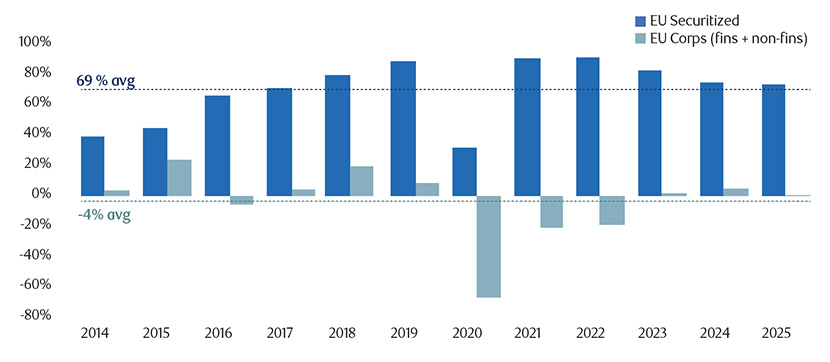
Natural deleveraging is another distinctive positive feature of securitized credit, with no direct equivalent in corporate bonds. As underlying loans make principal repayments, the payments flows through the waterfall, paying senior tranches first. As a result, the protective buffer for lower-rated tranches strengthens as senior tranches are paid down. A bond issued as a single-A can over time accumulate sufficient credit protection to meet the threshold for a single-A+ or AA rating, and may be upgraded accordingly. This structural dynamic explains why European securitized credit has historically generated more rating upgrades than downgrades – the reverse of the pattern observed in corporate credit markets. This is shown in figure 2.
Figure 2: Historical upgrade downgrade ratio for EU securitized credit and corporate credit
Source: Morgan Stanley, RBC BlueBay Asset Management, as at 31 December 2025. For illustrative purposes only. There is no assurance that any of the trends depicted or described herein will continue.
From an investor’s perspective, the risk from a portfolio of securitized credit bonds is, all else being equal, lower at the end of each year than it was at the start. In addition, active managers can identify bonds approaching an upgrade threshold and position ahead of the spread compression that typically follows.
How to access securitized credit?
Direct bond investment: investors can buy individual ABS, RMBS, CMBS or CLO tranches directly. However, large minimum investment sizes, and the necessary analytical capability to assess the collateral pool and structures means that this is suitable only for large institutions with dedicated structured credit teams.
Separately managed accounts/segregated mandates: asset managers can offer bespoke portfolios for single clients. These offer the advantage of greater customization, albeit with minimum investment thresholds.
Pooled funds: there are three types of pooled funds;
- Open-ended funds – offering daily or weekly liquidity and lower minimum investment thresholds – provide diversified exposure across ABS, RMBS, CMBS and CLOs, with specialist managers responsible for security selection, structural analysis and ongoing surveillance.
- Closed-ended funds: these can hold less liquid but more niche assets.
- ETFs: these offer liquid exposure to the asset class but are typically more focused on senior CLOs and so can lack the diversification available via other strategies.
Risks to consider
Securitized credit comes with several important risks that investors must consider. These include:
- Spread duration: although interest rate duration is typically low, spread duration is more meaningful, and spread widening can result in mark-to-market price declines, independent of underlying collateral performance. Senior tranches with faster amortisation are less exposed.
- Credit risk: Securitized credit is backed by observable collateral with structural protections that can absorb losses before they reach senior tranches. For investment grade tranches, the main consideration is the collateral type; senior CLO debt, consumer ABS, and CMBS structures carry different risk profiles, each of which rewards specialist analysis.
- Liquidity and mark-to-market risk: secondary market liquidity, notably mezzanine and CLO equity tranches, can deteriorate in risk-off environments such as during the GFC and March 2020. Bid-ask spreads can widen, with any forced sellers crystallizing mark-to-market losses on fundamentally sound positions.
- Pre-payment and extension risk: most relevant for mortgage and consumer ABS. Falling rates can accelerate prepayments, compressing yields and forcing reinvestment at lower spreads. Rising rates can slow them, extending duration beyond expectations. Active management can play a key role in managing this dynamic, especially in RMBS and consumer ABS.
- Structural design: cash flow distribution and loss absorption rules are built into the structure. Unlike corporate bonds, pricing relies on dealer quotes and model assumptions around borrower behaviour and default rates. Getting the structure right is as important as getting the credit call right.
While these risks in aggregate are meaningful, they are also manageable. For investors with the appropriate time horizon and risk tolerance, the structural characteristics of securitized credit can offer, in our view, attractive compensation relative to equivalently rated corporate alternatives.
Securitized credit: a mainstream asset class worth a closer look
Demand for securitized credit remains strong. Indeed, we expect the currently addressable US$1.3 trillion market available to European investors to continue to grow; driven by high-quality fundamentals, low correlation to traditional fixed income, predominantly floating-rate exposure and a spread premium that has historically compensated for structural nuance rather than inferior credit quality.
As an additional structural tailwind, we see a broadening institutional investor base, with regulatory changes in the insurance sector in Europe and the UK expected to drive demand in the next 3-5 years. This trend is also extending beyond Europe, with growing interest from investors across Asia, the US and the Middle East.
A broader, more diversified buyer base improves liquidity, reduces transaction costs, and provides stability of demand through market cycles. This backdrop reinforces the potential benefits to navigating securitized credit.